Can You Go to Jail for Not Paying Afterpay Debt? 9 Different Scenarios

It’s common sense to assume that when you don’t pay Afterpay, you could face late fees, account restrictions, and debt collection.
But can you actually get arrested for not paying Afterpay?
Whether you’ve missed one payment or have fallen several months behind, there are a few things you should know about what happens next.
You Won’t Go To Jail For Not Paying Afterpay
If you miss an Afterpay or Clearpay payment, you won’t be sent to jail simply because you couldn’t pay your bill.
In the United States, the United Kingdom, and Australia, ordinary unpaid consumer debt is handled through the civil legal system.
So, Afterpay can’t have you arrested just because you missed an instalment.
But you are not free from consequences.
Afterpay and Clearpay can charge late fees, restrict your account, and eventually send your unpaid balance to a debt collection agency.
Well, fraud is a different matter.
For example, deliberately providing false information to obtain credit could potentially lead to criminal consequences.
But simply falling behind on your Afterpay payments is not the same thing as committing a crime.
| Situation | Can you go to jail? | Note |
|---|---|---|
| You miss an instalment because you have no money | Generally, no | You cannot afford the payment. This is normally a civil debt issue. |
| You lose your job and cannot pay | Generally, no | Losing your income and being unable to repay is not normally a crime. |
| You stop paying Afterpay altogether | Generally, no | Afterpay may pursue the unpaid debt through collection processes. |
| You ignore payment reminders | No, not by itself | Ignoring reminders does not automatically become a criminal offence. |
| You close your bank account while owing money | No, not by itself | You still owe the debt, but closing an account alone is not normally a crime. |
| You have multiple unpaid Afterpay purchases | Generally, no | Having several unpaid purchases does not automatically mean fraud. |
| You deliberately use someone else’s identity | Potentially, yes | Identity theft or impersonation can be criminal offences. |
| You use stolen cards or fraudulent information | Potentially, yes | This may constitute payment fraud or identity theft. |
| You intentionally commit fraud to obtain purchases | Potentially, yes | Deliberately deceiving a company to obtain goods can be a criminal offence. |

Can You Use Afterpay on Cash App?
Wondering whether Afterpay works with Cash App? Find out how the services work together, what payment options may be available, and what to check before trying to use them.
CHECK HOW AFTERPAY WORKS WITH CASH APP →Afterpay Can Charge You Late Fees
When you miss an Afterpay payment, you’ll be charged a late fee.
Here’s how the fees generally work:
| Country | If You Miss a Payment | If Still Unpaid After 7 Days | Fee Limit |
|---|---|---|---|
| USA | Up to $8 | No additional 7-day fee specified | 25% of order value |
| UK (Clearpay) | £6 after 1 day | Additional £6 | 25% of purchase price |
| Australia | A$10 the next day | Additional A$7 | Lower of 25% of order value or A$68 |
Keep in mind that these are late fees, not interest charges.
Pay-in-4 plans don’t charge interest, but missed payments can still make your purchase more expensive.
Afterpay Account Could Be Frozen
If you miss your payments, you could lose access to your Afterpay account.
Afterpay and Clearpay generally restrict your ability to make additional purchases when you have an overdue balance.
For example, if you miss an instalment, you may find that your:
- Spending limit is reduced.
- You can’t make new purchases using Afterpay.
- Account remains frozen until you catch up on payments.
- Repeated missed payments could result in your account being permanently closed.
Why does this happen?
Afterpay wants to limit its exposure to customers who already have outstanding balances. If you haven’t paid for previous purchases, the company may decide that you’re no longer eligible to make additional purchases.
But account restriction isn’t permanent. Depending on your circumstances, bringing your payments up to date may allow you to use the service again.
You Still Owe The Money Even If The Merchant Was Paid
I’ve heard a few times now that people are confused about Buy Now, Pay Later services and who they’re actually responsible for paying.
When you purchase something through Afterpay, the merchant is generally paid by Afterpay, while you agree to repay Afterpay through instalments.
This means that if you miss an Afterpay payment, it doesn’t automatically cancel your original purchase.
So, your payment problem is generally with Afterpay rather than the retailer.
Can Afterpay Sue and Send You to Collections?
Yes, if you continue ignoring your outstanding payments, Afterpay or Clearpay may eventually involve a debt collection agency.
This is the same as what happens with other unpaid consumer debts, such as credit card balances and personal loans.
| Country | Send to Debt Collectors? | Can They Sue You? |
|---|---|---|
| USA | Yes, unpaid debt can be sent to collection agencies. | Yes, legal action may be possible. |
| UK (Clearpay) | Yes, unpaid balances may go to debt collectors. | Yes, they may pursue legal recovery. |
| Australia | Yes, Afterpay can use debt collection agencies. | Yes, they may take legal action. |
| Austria | Yes, unpaid balances may go to debt collectors. | Yes, they may take legal action. |
Afterpay’s Australian terms allow the company to appoint collection agencies to recover outstanding amounts. Clearpay UK also warns that unpaid balances may be referred to debt collectors.
Afterpay US similarly reserves the right to transfer or sell debts and use collection services.
So, what does this mean for you if you are in the same situation?
If your account is sent to collections, you may start receiving:
- Phone calls from debt collectors.
- Letters requesting payment.
- Emails about your outstanding balance.
- Requests to arrange a repayment plan.
By the way, you shouldn’t automatically assume that a collection notice means you’re being sued.
Debt collectors generally try to recover the money without taking the matter to court.
But you shouldn’t ignore legitimate collection notices.
Will Not Paying Afterpay Affect Your Credit Score?
Afterpay Pay-in-4 purchases in the United States and Australia have generally not been reported as ordinary repayment activity to credit bureaus.
| Country | Credit score affected? | Note |
|---|---|---|
| USA | Generally no | Standard Pay-in-4 missed payments aren’t reported to credit bureaus. |
| Canada | Generally no | Late instalments generally aren’t reported to credit bureaus. |
| Australia | Usually no | Pay in 4 repayment history isn’t currently reported, but some credit checks may appear on your report. |
| New Zealand | Yes | Late payments can be reported to credit bureaus and may lower your score. |
| UK (Clearpay) | May do | Missed payments may be reported and could make future borrowing harder or more expensive. |
What Should You Do If You Can’t Pay Afterpay?
If you’re struggling to make your Afterpay payments, the worst thing you can do is simply ignore the problem.
Instead, there are several things you can try.
1) Contact Afterpay As Soon As Possible
If you know you’re going to miss an upcoming payment, contact Afterpay or Clearpay through its official app or customer support channels.
Explain your situation and ask what options are available.
Depending on your circumstances and country, you may qualify for hardship assistance or a payment arrangement.
2) Ask About Changing Your Payment Date
In some circumstances, Afterpay may allow you to change an upcoming payment date through the app.
This can be helpful if your payment is due before your next paycheck arrives.
3) Ask About Financial Hardship Assistance
If you’ve
- Lost your job
- Experienced an unexpected expense
- Or are dealing with another financial difficulty, ask whether the company offers hardship assistance.
For example, Afterpay Australia’s terms encourage customers experiencing payment difficulties to get in touch and discuss possible options, including payment deferrals.
4) Don’t Ignore Debt Collectors
If your outstanding balance has already been referred to collections, please don’t go incognito; make sure you respond appropriately.
Verify the collection agency, request information about the debt if necessary, and understand your rights before agreeing to a repayment arrangement.
Also, don’t promise to pay an amount that you realistically cannot afford.
What Happens If You Ignore Debt Collectors?
Find out what collectors can do if you don’t respond, when a lawsuit may follow, and how ignoring collection notices could affect you.
Check the Consequences →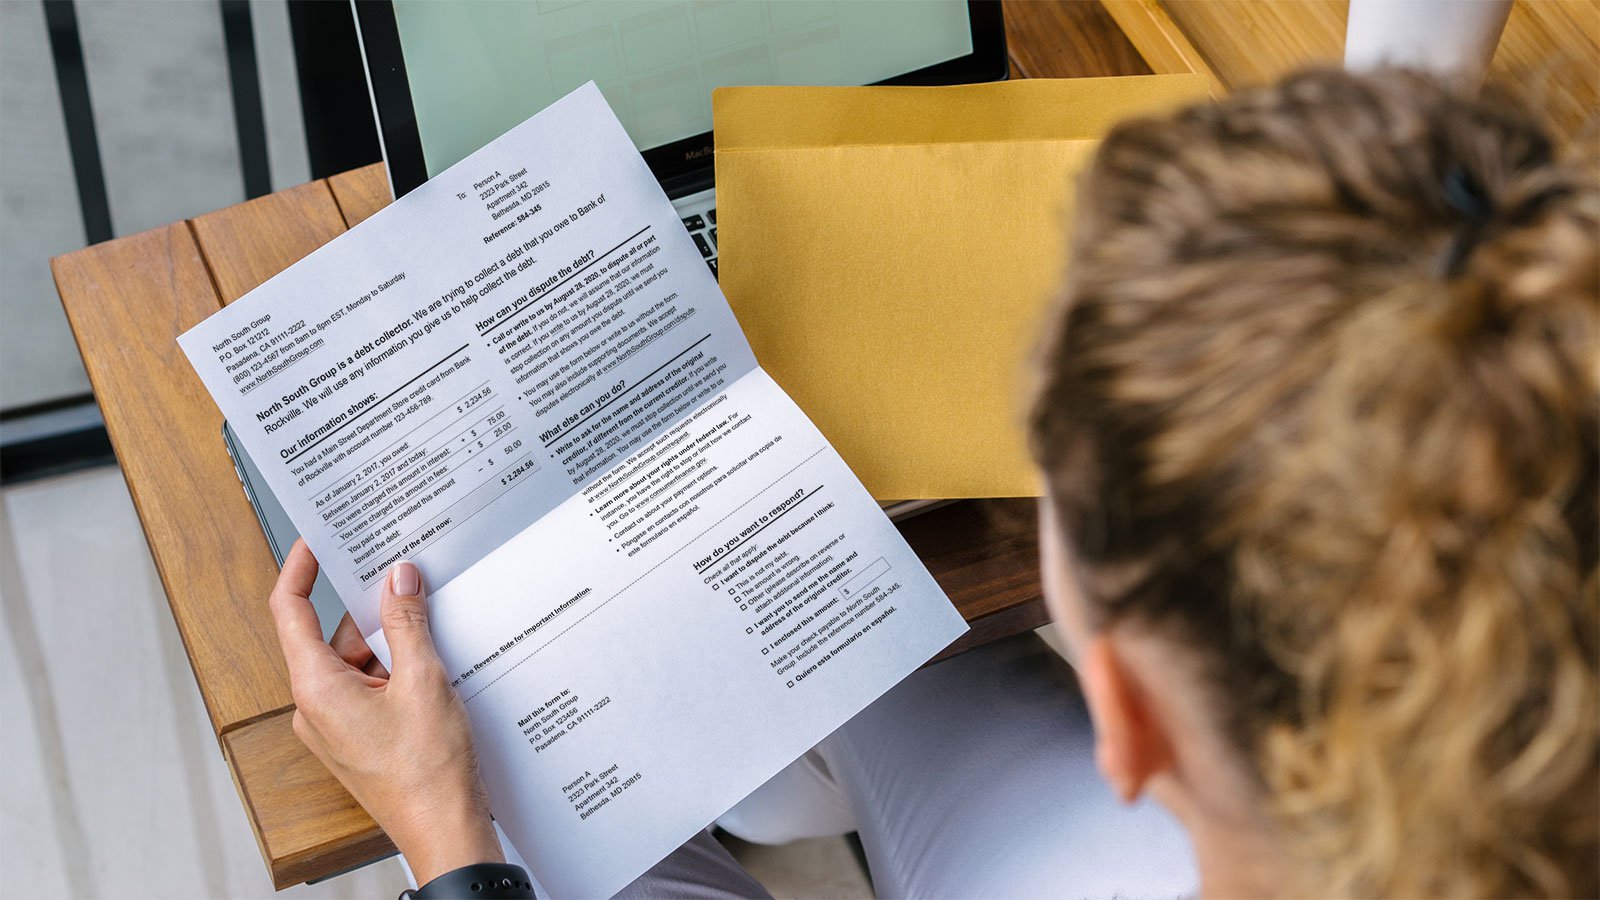
So, if you don’t pay Afterpay or Clearpay, you could face late fees, account restrictions, debt collection, and potentially legal action.
But you won’t go to jail simply because you missed a Buy Now, Pay Later payment.
References: